On this page
The right analysis of an alternative investment return starts with the way that return was produced. Irregular cash flows need a time-aware measure, infrequent valuations need a check on price quality, and asymmetric payoffs need more than a mean and standard deviation. A CAIA® Level I candidate should diagnose those features before reaching for a familiar ratio.
Start with the return-generating structure
The CAIA Level I curriculum overview includes alternative investments, statistical foundations and quantitative foundations. Those subjects belong together when analysing an asset: an investment labelled alternative does not automatically require every specialist tool. A liquid listed vehicle and a privately negotiated fund interest can have different reporting and cash-flow mechanics even when both expose the holder to the same economic sector. Identify the observation you have, the economic return you want, and the constraint that may make the observation misleading.
Begin by drawing a timeline of money entering and leaving the position. Ask whether the quoted return belongs to an investible asset price, a fund unit value, or a series of investor cash flows. A price return between two observable dates can be calculated directly. A private fund with capital calls and distributions creates a different question: the investor parts with different amounts of capital for different lengths of time. Averaging its reported periodic percentages can erase that timing.
Next identify who supplies the price. A traded closing price, a manager estimate, and an external appraisal have different evidential weight. An appraisal may be careful and still arrive after the underlying market has moved. The distinction is about measurement, not a claim that one party is dishonest. CAIA Association notes in its curriculum guidance that the official curriculum is the anchor for the exam year. Use current material to confirm the exact syllabus for your sitting.
Choose a method for the problem in front of you
| Uneven contributions and distributions | What did the investor earn on timed capital? | Cash-flow timeline and money-weighted return |
| Sporadic assessed values | Would a sale today match the reported value? | Valuation basis and transaction evidence |
| Losses cluster in adverse states | How large can bad outcomes be beyond a threshold? | Downside and tail analysis |
| A claimed diversifier | Does co-movement survive stressful periods? | Conditional correlation and scenario review |
The table is a diagnostic, not a ranking of performance measures. An internal rate of return can answer a timing question but cannot establish that an interim valuation was fair. A downside measure can reveal an asymmetric loss pattern but cannot make an illiquid holding sellable. One sound analysis may therefore combine a cash-flow measure, a valuation challenge, and a liquidity scenario rather than choose a single headline number.
Diversification claims also require care. A strategy can be designed for an absolute return objective yet still lose money when a common financing source disappears or when several managers must sell similar positions. A low correlation estimated from quiet periods is a description of that sample. It is not proof of independence in a stressed market. Examine how exposures and funding needs might change at the same time as the underlying asset prices.
An illustrative cash-flow comparison
Consider two invented investments with no fees, taxes or interim valuation. Each starts with a contribution of 100. Investment A returns 110 after one year. Investment B returns 121 after two years. The total cash profit is 10 for A and 21 for B, so a simple ranking by pounds earned would prefer B. That ignores how long the initial capital was committed. The figures are deliberately round and are only a teaching example, not observed market returns.
For A, a 10% annual money-weighted return makes the initial 100 grow to 110 in one year. For B, the same annual rate compounds the initial 100 to 121 over two years. Their annualised returns are therefore equal despite different total cash profits. Conversely, an asset returning 121 after one year would have a 21% annual return. The calculation changes the conclusion because the investment periods differ, not because a longer hold is inherently worse.
Now add a valuation issue. Suppose B reports an interim estimate of 115 at the end of year one but cannot be sold then. That estimate is a data point about the manager’s view; it is not a realised exit. If the final proceeds remain 121, the investor’s two-year cash-flow result is unchanged. If an exam vignette asks for a realised investor return, treat the interim estimate separately from the cash-flow calculation. If it asks about portfolio volatility, the estimate enters the reported return series and may change its apparent smoothness.
Where standard deviation can understate the concern
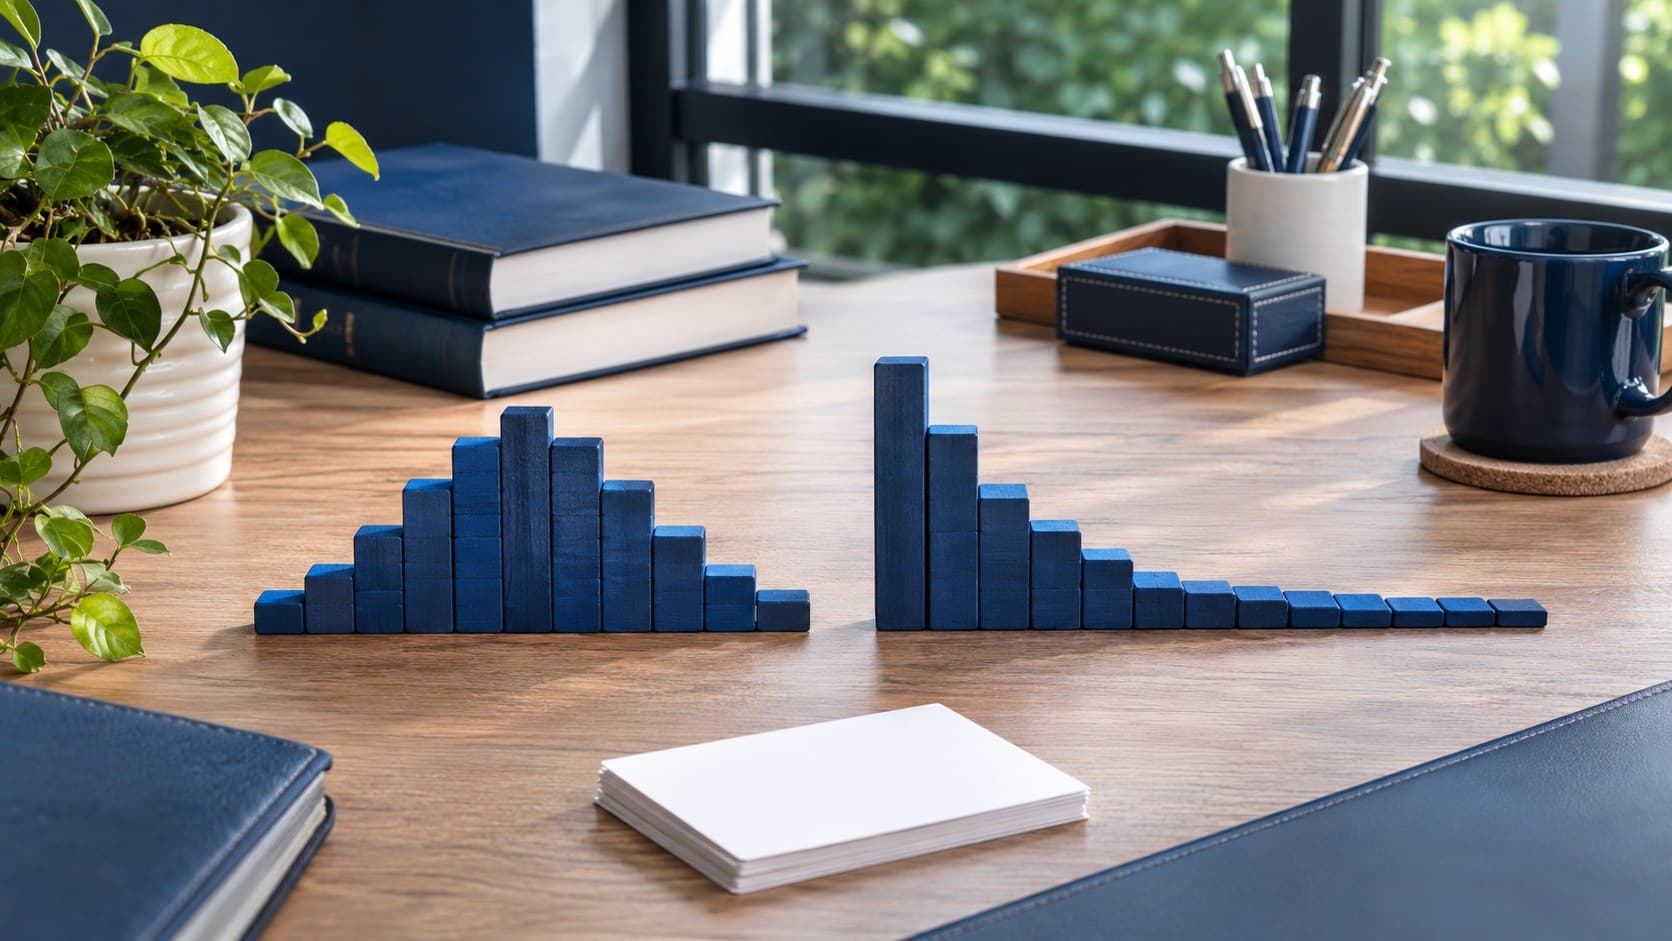
A mean and standard deviation summarise location and dispersion. They do not by themselves identify whether unusually large negative outcomes are more likely than unusually large positive ones, whether an option-like strategy has a sharp loss boundary, or whether observations were smoothed by valuation practice. The current CAIA Level I overview includes statistical foundations alongside alternatives. A candidate should therefore inspect the shape and source of the observations before making a normal-distribution assumption.
A simple thought experiment makes the limitation concrete. One strategy earns a small positive amount in most observed months but occasionally pays a large loss. Another oscillates around a similar average more symmetrically. Their standard deviations can be made equal by choosing the magnitudes carefully, yet an investor with a strict cash reserve may care much more about the first strategy’s loss when it occurs. A downside threshold, expected shortfall or explicit bad-state scenario addresses a question the single dispersion figure leaves open. It still depends on credible data and stated assumptions.
The observation interval matters too. Private assets may be revalued quarterly rather than traded continuously. A reported series can look steady because information arrives slowly, while an actual sale would require a discount or a long search for a buyer. Do not infer that a small reported standard deviation proves low economic risk. Compare the valuation policy with transaction evidence where available and ask whether a delayed write-down is plausible.
Treat liquidity as a cash-flow constraint
Illiquidity is not just a return premium to add in a formula. It means the investor may be unable to sell at the time or price needed. A fund interest can also generate new capital calls while the investor is waiting for distributions. The analysis must ask whether cash reserves can meet obligations under a difficult scenario. A favourable long-run expected return does not settle a near-term funding problem.
For an exam answer, keep three layers separate: economic exposure, reported value and investor cash flow. Economic exposure asks what can drive gains and losses. Reported value asks how the number on the statement was produced. Investor cash flow asks when the holder actually supplies or receives money. Confusing those layers leads to errors such as treating a valuation increase as cash available to meet a capital call, or treating an attractive IRR as evidence that a fund can be exited promptly.
A practical exam decision sequence
- Read the requested output first: annual investor return, portfolio risk, valuation reliability and liquidity capacity are different tasks.
- Mark every dated contribution and distribution before computing a return. State the time unit and do not silently equate total profit with annual performance.
- Identify whether prices are traded, estimated or appraised. A figure can be arithmetically correct yet economically stale.
- Inspect whether downside risk, leverage or nonlinear payoffs make a symmetric model unreliable. State the assumption rather than hiding it.
- Conclude with the narrow answer supported by the data. A diversification claim requires evidence about co-movement, especially when conditions change.
This sequence also helps revision. The CAIA program page locates the subject in the wider course, while the methodology page explains the study approach. Use them to decide where to practise, then return to the official CAIA curriculum for the precise learning objective. The durable lesson is methodological: match the measurement to the economic question and state what the available observations cannot show.
Sources
- Explore the Curriculum | CAIA Association · caia.org · Retrieved
- Curriculum and Study Tools | CAIA Association · caia.org · Retrieved
- Strategic Asset Allocation: Practical Considerations for Alternative Investments | CAIA Association · caia.org · Retrieved


