On this page
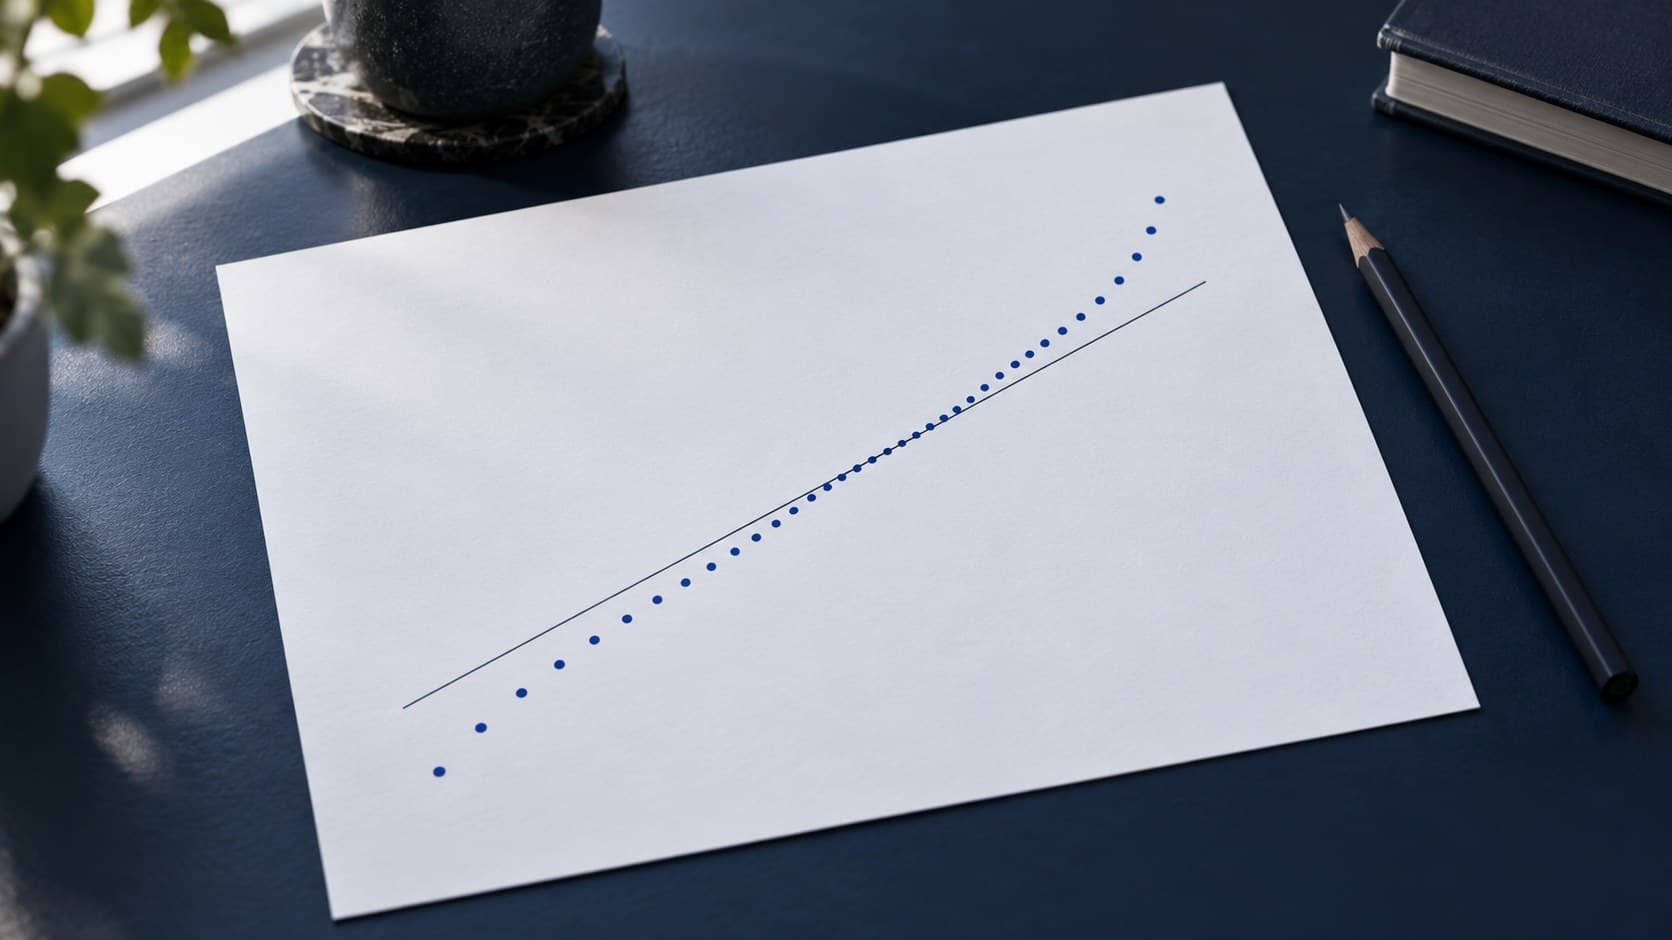
On a normal Q-Q plot, a left tail below the reference line and a right tail above it suggest that the observed returns have more extreme outcomes than a normal reference with the same scale. That is a warning about the distributional assumption, not a numerical estimate of loss probability or value at risk. First check which quantity is on each axis and how the reference line was fitted.
What the dots compare
A quantile-quantile plot pairs each ordered observation with the quantile a reference distribution would produce at a corresponding rank. Here, put theoretical normal quantiles on the horizontal axis and observed returns on the vertical axis. A close run along the reference line means the sample resembles that normal model at those ranks. A systematic bend shows where the fit deteriorates.
This matters in market risk because a model fitted to the centre can describe ordinary returns reasonably while missing the tails. GARP lists Market Risk Measurement and Management in its FRM Part II study materials. A research paper hosted by GARP uses a probability plot to compare observed commodity returns with normal and t references and discusses departures in the tails.
Read an illustrative plot from left to right
Consider seven invented, already ordered return observations, measured against a fixed zero-mean, unit-scale normal reference: negative 2.5, negative 0.6, negative 0.2, zero, positive 0.2, positive 0.6 and positive 2.5. These are illustrative values, not market data. Compare them with fixed standard-normal quantiles at the same ranks, using plotting positions midway through each rank.
| Lowest | negative 1.47 | negative 2.5 |
| Middle | zero | zero |
| Highest | positive 1.47 | positive 2.5 |
The lowest observed return is below its normal-reference point; the highest is above. The middle pair agrees. With the stated axis order, the ends bow outward, which is the visual pattern of heavier tails than that reference. The table displays only the end and middle pairs so that the direction is easy to inspect; the full plot would show every observation.
Avoid the common interpretation traps
- Read the sign, then the magnitude. A leftmost point below the line is more negative and therefore a larger loss in absolute terms, assuming returns are on the vertical axis.
- Check the axis order. If observed returns are horizontal instead, the visual directions reverse; identify the axes before naming a tail pattern.
- Separate shape from scale. A generally tilted straight line may reflect a different dispersion rather than unusually heavy tails. A shifted straight line may reflect a different centre.
- Keep inference modest. The plot flags a model-checking problem. It does not itself select a replacement distribution or calculate a tail-risk measure.
When revising this topic, sketch the reference line and place the three illustrative pairs before reading a verbal description. The FRM program overview and Omni study methodology provide the wider study context.
Sources
- FRM® Study Material, Guide, Books, Practice Exams | GARP · garp.org · Retrieved
- Portfolio Stress Testing Applied to Commodity Futures · garp.org · Retrieved


