When ESG research should change strategic asset allocation
Concept
Material ESG research can change asset-class assumptions as well as security analysis. Trace the evidence through a simple return example and the portfolio process.
· 3 min
New to Omni?·Get 20% off your first purchase with code WELCOME20 at checkout.See plans
Short, specific writing on the CFA, FRM, CAIA, CFP and ESG programs — exam strategy, curriculum shifts and what the charter actually signals. Written for candidates who are sitting, not browsing.
Page 5 of 7
Material ESG research can change asset-class assumptions as well as security analysis. Trace the evidence through a simple return example and the portfolio process.
· 3 min
CFP Board’s exam format gives each timed session a shared clock across two subsections. Calculate a workable average, then protect time for case studies and review.
· 3 min
An emergency fund is judged against essential spending and the household’s likely income gap. Work through coverage, a reserve target and the errors to avoid.
· 2 min
Catastrophe bond triggers can follow the insurer’s claims, an industry index, physical readings or a loss model. The choice changes payout timing and basis risk.
· 2 min
A commercial property loss reaches common equity before mezzanine debt and senior mortgage debt. Follow an illustrative waterfall and connect it to underwriting.
· 2 min
A GARCH forecast combines a recent shock, prior variance and a long-run anchor. Work through the update, then check whether the fitted variance can mean-revert.
· 2 min
Portfolio delta can cancel while gamma and vega remain. Use signed option counts, a consistent unit basis and a worked book to see what the totals mean.
· 3 min
The futures price reflects the cost and benefit of holding the asset to delivery. Trace a simple replication, calculate a price, and separate it from a forecast.
· 3 min
A selling price is not net realisable value. Work through an inventory batch, subtract the costs still needed to finish and sell it, then measure the write-down.
· 2 min
A short recall session after a reading, followed by spaced returns to the same ideas, can fit around work. Use this weekly example and adjust it to your errors.
· 2 min
Passing the CFP exam is only one CFP Board requirement. Check the degree, experience and ethics evidence still due, then finish certification before using the marks.
· 2 min
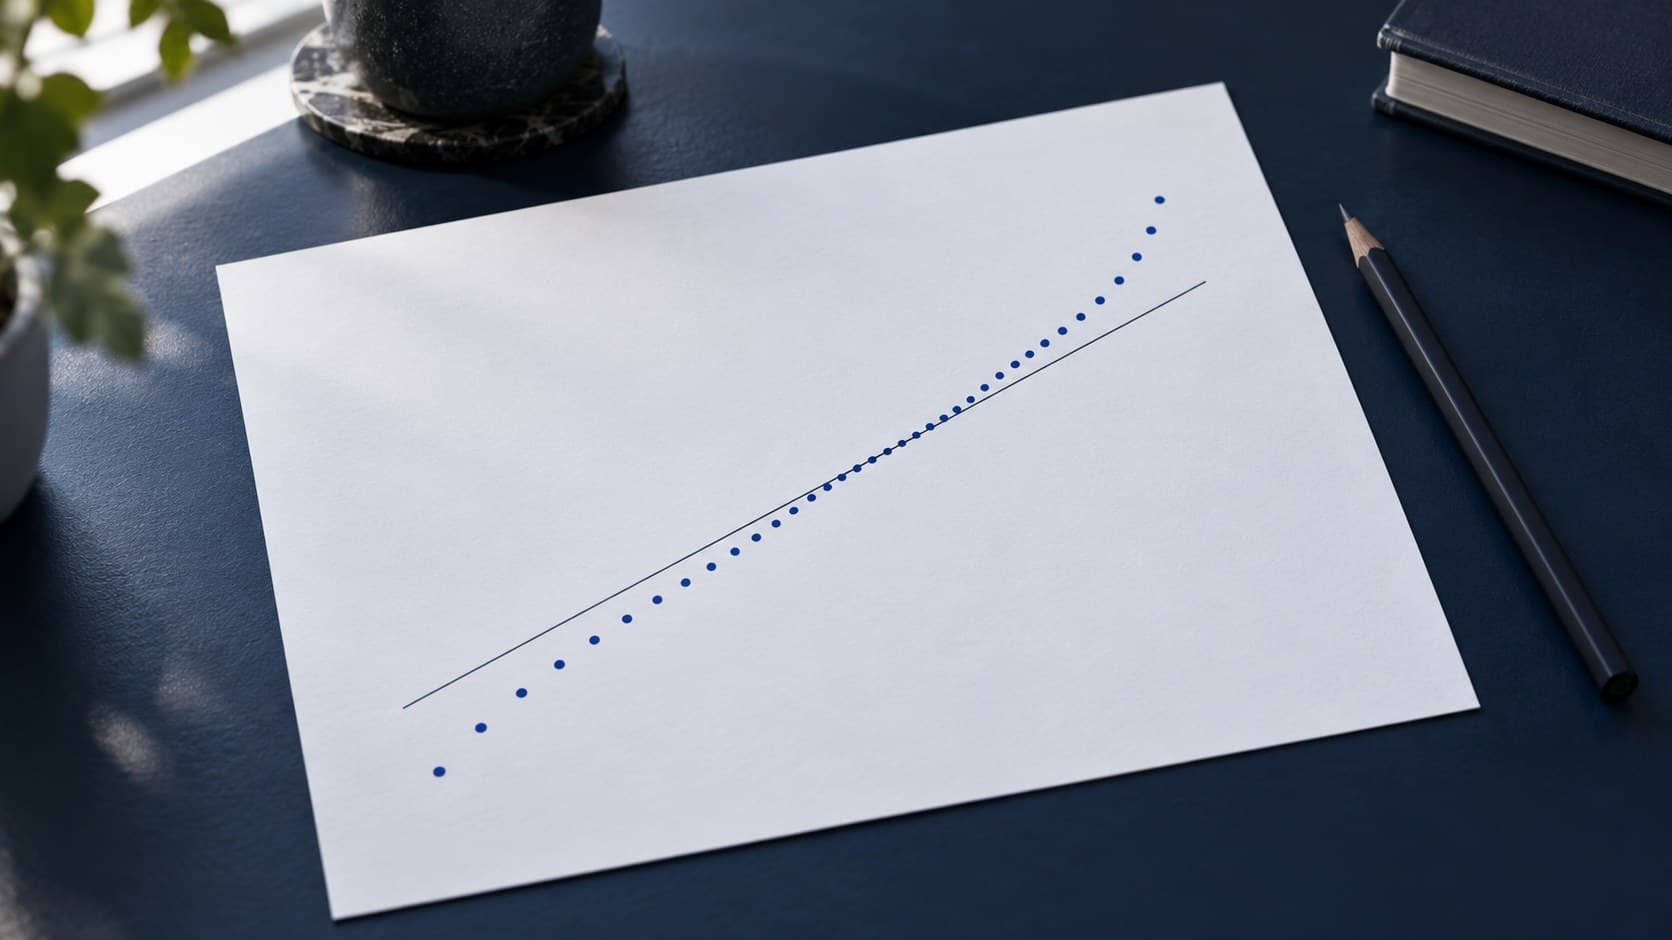
A normal Q-Q plot compares ordered returns with normal quantiles. Read outward tail bends, check the axes, and avoid mistaking a visual clue for a risk estimate.
· 2 min
A climate factor matters financially when it changes cost, revenue or asset assumptions. Follow a carbon-price scenario and test opportunity claims separately.
· 3 min
A manager’s average excess return is only a starting point. Check the benchmark, active-risk variability and attribution before treating a track record as skill.
· 2 min
Retirement capital is the present value of planned withdrawals at the retirement date. Work through a real-return example and avoid timing and inflation errors.
· 2 min
Price, equal and market-capitalisation weights give stocks different influence. Calculate all three returns from one invented example and learn the exam trap.
· 2 min
Common-size income statements show lines as a share of revenue, letting you compare margins across firms and periods. See a worked example and the denominator trap.
· 2 min
A group surplus can conceal a parent-bank funding gap when subsidiary cash cannot move under stress. Learn how scope and transfer assumptions change the result.
· 2 min
A property can support direct equity, a mortgage or a listed share. Separate the claim, access route and investment style before comparing its risk or liquidity.
· 3 min
Active return tests a manager against a benchmark; the Sharpe ratio scales excess return by total volatility. Work through both without mixing reference points.
· 2 min
A falling price can trigger an old reference point or a painful reaction to loss. Separate them in a CFP® planning conversation without labelling the client.
· 2 min
Subadditivity says combined risk should not exceed the sum of stand-alone risks. A loss table shows why value at risk can fail while expected shortfall holds.
· 2 min
The same quoted annual rate produces different growth and discount factors when compounding changes. Work through annual and quarterly cases, avoid a common mix-up.
· 2 min
A fixed exclusion and a within-sector ranking can produce very different portfolios from the same issuers. Learn how to apply each rule and check benchmark drift.
· 2 min